Equinix extends European cloud footprint by buying AM11 data centre


Clare Hopping

24 Apr, 2019

Equinix has bought Switch Datacenters’ AMS1 data centre business in Amsterdam in a deal worth €30 million.

The data centre provider already owns ten data centres in the Netherlands, with eight of these in Amsterdam itself. This newest addition will further boost Equinix’s hold on the Dutch market and increasing its worldwide users to 3.9 billion.

The site not only has the capacity for an additional 700 cabinets, it’s also located in a place that will enable it to expand to an adjacent building with space for another 1,300 cabinets.

«The Netherlands and especially the Amsterdam Metropolitan Area is a top destination for global businesses looking to expand into Europe,” said Peter van Bergel CEO of AMS-IX, a long-standing customer and partner of Equinix. 

“There is access to a highly educated and multilingual workforce and a state-of-the art technology infrastructure to meet the digital needs of these businesses.”

He added that businesses are demanding more data centre capacity and interconnectivity and through the purchase, Equinix will be able to address this, while AMS-IX can continue to contribute to the landscape.

Equinix’s AM11 data centre will interconnect with its AM7 data centre, providing a wealth of business services to both existing AMS-IX customers and Equinix clients.

«Amsterdam is a key interconnection point for Europe, with leading enterprises and cloud service providers making it a primary hub for IT infrastructure,” Eugene Bergen, EMEA president at Equinix.

“Adding interconnection capacity in this market enables local and international customers to leverage Platform Equinix to meet their changing business needs. Whether that is to connect to networks, clouds, or content and digital media providers, Equinix is the place to be.»

Salesforce upgrades Sales Cloud with productivity tools


Clare Hopping

24 Apr, 2019

Salesforce has unveiled a raft of productivity features for its Sales Cloud software, helping users save time completing arduous tasks such as admin.

One of the headline features of the Sales Cloud update is the ability for users to view all customer information from their mobile or desktop email inbox. Rather than just being able to see the sender’s name, they are now able to view extra data pulled in from Salesforce, such as account details, contacts and opportunities to discuss at their next meeting.

Additionally, actions are surfaced following meetings, so they can be monitored and ticked off when completed. Notifications are also sent at key milestones, such as when pricing is discussed or a deal is closed.

From a campaign perspective, the Einstein Campaign Insights feature can group together prospects likely to engage with a particular campaign so they can be retargeted with similar campaigns that are likely to result in success. Both sales and marketing teams will have access to these key insights, offering the opportunity to unify efforts across the two departments for conversion.

Sales Cloud’s Social Intelligence Module surfaces an AI-powered social media feed to present conversations to sales teams. These are pooled together from various data points and presented in an easy to digest way, so salespeople can make sure their efforts are in line with their prospects’ expectations. These insights can also be shared with other team members using Chatter.

For High Velocity Sales tool, Salesforce has added sales cadences and work queues to help identify and perfect pitches to new prospects. Complex sales funnels can be addressed with linked sales cadences and work queues can be customised to display the most important prospects’ details in one place.

“With these new productivity features, we’re managing the flow of information so that what you need is surfaced when you need it, all within Sales Cloud,” said Robin Grochol, SVP of product management for Sales Cloud at Salesforce.

“It’s about making every rep more efficient, guiding their focus to the most impactful accounts and tasks, and elevating and upskilling every individual’s performance.”

How channel partners are driving hyperscale cloud growth

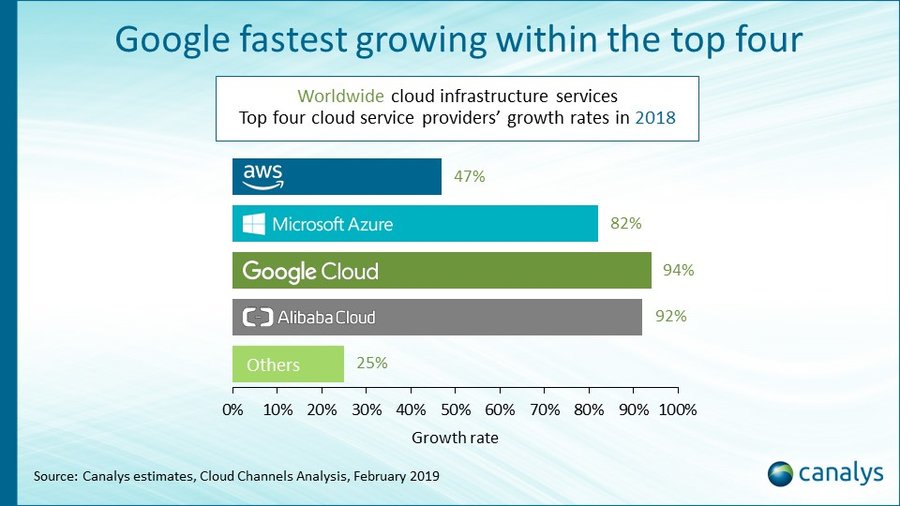
Hyperscale cloud service providers continue to leverage their low-cost advantage to drive growth. According to the latest worldwide market study by Canalys, Google Cloud was the fastest-growing cloud infrastructure vendor last year – up more than 90% year on year – increasing its share of the total market from 6% in 2017 to 8% in 2018.

The top four hyperscale cloud service providers accounted for 61% of the total market in 2018. Amazon Web Services (AWS) remained the leader on 32%, followed by Microsoft Azure with 17%, Google Cloud in third place with 8% and Alibaba Cloud with 4%.

Hyperscale cloud market development

Canalys reports that hyperscale cloud infrastructure services are in a period of sustained growth, with spending up 46% in 2018 to more than $80 billion. Expenditure is also forecast to surpass $143 billion in 2020.

More businesses are deploying a hybrid multi-cloud strategy, integrating multiple providers with their existing on-premises IT infrastructure. Canalys estimates 30% of cloud infrastructure services spend, just over $24 billion, went through the IT channel of distributors, resellers, service providers and systems integrators in 2018.

"AWS, Microsoft Azure, Google Cloud and Alibaba Cloud are all increasing channel investment to raise their profiles, as competition for enterprise customers increases and workload cloud migration diversifies," said Alastair Edwards, chief analyst at Canalys.

The channel will play a vital role for the cloud service providers, in terms of boosting their customer reach, from both a sales and technical perspective. But each of the hyperscale cloud service provider titans current partner reach, engagement and program maturity differs — with Google Cloud trailing both AWS and Microsoft Azure in all areas. Alibaba Cloud is further back, behind the leaders.


Canalys estimates the top three providers represented 65% ($16 billion) of the channel's total cloud infrastructure services business in 2018. Microsoft manages one of the largest channel ecosystems in the technology sector and its Cloud Solution Provider (CSP) program is the most mature among the cloud titans, according to the Canalys assessment.

Approximately 74% of revenue from Azure is estimated to come via its partners, which is by far the highest percentage in the sector. In contrast, AWS channel business accounts for around 15%, though its reach is growing rapidly, AWS having recruited over 35,000 partners to date, with hundreds a month wanting to join its partner program.

Canalys estimates that Google Cloud's channel business accounts for just over 25% of its $7 billion cloud infrastructure revenue. In spite of Google Cloud's rapid growth, its channel reach is relatively small, though it is trying a differentiated approach by being more focused on specific applications and verticals.

An estimated 13,000 partners have joined its partner program, of which just over 100 have achieved the highest-tier Premier Partner status, while less than a third of those have achieved a Specialization Partner designation.

Outlook for cloud channel application growth

In a recent Candefero channel survey, 20% of respondents think there is huge potential to working with Google Cloud, while 22% said they will work with other cloud service providers instead. Cloud computing service channel partners will continue to align with the market leaders.

That said, 44% of partners were intrigued to know more about partnering with Google. Their new leadership brings the experience of working with the largest enterprise customers. But to date, Google has not captured the broader channel where AWS and Microsoft are being more proactive.

https://www.cybersecuritycloudexpo.com/wp-content/uploads/2018/09/cyber-security-world-series-1.pngInterested in hearing industry leaders discuss subjects like this and sharing their experiences and use-cases? Attend the Cyber Security & Cloud Expo World Series with upcoming events in Silicon Valley, London and Amsterdam to learn more.

Intel Named «Technology Sponsor» of @CloudEXPO | @Intel @IntelSoftware @ZhannaGrinko #HybridCloud #HybridIT #AI #AIOps

Intel is an American multinational corporation and technology company headquartered in Santa Clara, California, in the Silicon Valley. It is the world’s second largest and second highest valued semiconductor chip maker based on revenue after being overtaken by Samsung, and is the inventor of the x86 series of microprocessors, the processors found in most personal computers (PCs). Intel supplies processors for computer system manufacturers such as Apple, Lenovo, HP, and Dell. Intel also manufactures motherboard chipsets, network interface controllers and integrated circuits, flash memory, graphics chips, embedded processors and other devices related to communications and computing.

read more

CFP Deadline For @DevOpsSUMMIT Silicon Valley April 30 | #Cloud #CIO #APM #CloudNative #Servelress #DevOps

The widespread success of cloud computing is driving the DevOps revolution in enterprise IT. Now as never before, development teams must communicate and collaborate in a dynamic, 24/7/365 environment. There is no time to wait for long development cycles that produce software that is obsolete at launch. DevOps may be disruptive, but it is essential.

DevOpsSUMMIT at CloudEXPO expands the DevOps community, enable a wide sharing of knowledge, and educate delegates and technology providers alike.

read more

Apptio Named «Bronze Sponsor» of @CloudEXPO | @Apptio #HybridCloud #Cloud #CIO #AI #MachineLearning #DeepLearning

Apptio fuels digital business transformation. Technology leaders use Apptio’s machine learning to analyze and plan their technology spend so they can invest in products that increase the speed of business and deliver innovation. With Apptio, they translate raw costs, utilization, and billing data into business-centric views that help their organization optimize spending, plan strategically, and drive digital strategy that funds growth of the business. Technology leaders can gather instant recommendations that result in up to 30% saving on cloud services. For more information, please visit www.Apptio.com.

read more

Japan DX Pavilion at @CloudEXPO Silicon Valley | @JETROUSA @IDE_JETRO #Cloud #CIO #IoT #DevOps #Blockchain #SmartCities

The Japan External Trade Organization (JETRO) is a non-profit organization that provides business support services to companies expanding to Japan. With the support of JETRO’s dedicated staff, clients can incorporate their business; receive visa, immigration, and HR support; find dedicated office space; identify local government subsidies; get tailored market studies; and more.

read more

CloudBlue | Ingram Micro to Exhibit at @CloudEXPO | @IngramMicroInc #HybridCloud #HybridIT #AI #AIOps #SaaS #PaaS #DigitalTransformation

After years of investments and acquisitions, CloudBlue was created with the goal of building the world’s only hyperscale digital platform with an increasingly infinite ecosystem and proven go-to-market services. The result? An unmatched platform that helps customers streamline cloud operations, save time and money, and revolutionize their businesses overnight.

Today, the platform operates in more than 45 countries and powers more than 200 of the world’s largest cloud marketplaces, managing more than 27 million enterprise cloud subscriptions valued at more than $1 billion in revenue.

read more

Digital transformation in the financial services industry


Stuart Andrews

18 Apr, 2019

Like most industries, the financial services sector is going through an intense period of digital transformation. A recent Gartner survey found that one-third of financial services CIOs identified going digital as their top business priority for 2019 – up by more than 8% from the response the year before. Meanwhile, a report last year from the World Economic Forum suggests that AI, along with Blockchain, Cloud and – in the future – Quantum Computing, could transform what it calls ‘the physics of financial services’ – ‘weakening the bonds that have historically held together financial services and creating new centres of gravity where new and old capabilities are being combined in unexpected ways.’

Together, the combination of big data, AI, cloud and mobile is empowering firms to move away from their old processes and business models and embrace new opportunities. The most visible impact is on the customer experience, as cloud-based services, voice interactions, bots and mobile apps give us new ways to interact with financial products and services. However, as much is going on behind the scenes. Some banks are digitising their internal processes, moving away from paper-based filing and legacy applications to modern, cloud-based services that aid compliance and allow them to extract more value from the data.

Meanwhile, robotic process automation is helping firms to automate complex, time-intensive activities, while AI technologies turn data into insight, providing decision-making support for human workers. Natural language processing technologies will impact everything from customer interactions to compliance, helping firms to both extract crucial information from unstructured data and put those findings to good use. And when you have the computing power to combine real-time data streams with analytics and AI, you have the ingredients you need to optimise your processes and make effective decisions faster.

Perhaps most crucially, digital transformation is helping financial services firms reinvent themselves. The sector is slowly moving from an era of competition to one of collaboration, where established institutions can partner with new FinTechs to create personalised, intelligent, cloud-based solutions that can meet customer expectations while simultaneously lowering operating costs. Transformation isn’t about offering the same products and services through new technology, but about making services more personal to each customer and more accessible to a wider market. That’s why banks like ABN AMRO in the Netherlands are maintaining office space where they can work directly with new start-ups to drive innovation.

This more collaborative environment is also being fuelled by the growth of Blockchain, enabling networks where everyone who needs to can have access to the same data, with all changes to that data recorded and locked-in. Everyone can work using the same ‘shared truth.’

Meeting the challenge

Firms understand the necessity of this transformation. In the words of ABN Amro COO Johan van Hall, ‘Banks are in a very transformational mode. We see the new entrants coming and we believe that banks towards the end of the decade will be very different than we are today.’ Flexibility, agility and speed have become key goals.

Of course, financial services organisations face specific challenges. As well as the universal issues around data regulation and GDPR, they’re bound by industry regulations designed to ensure that institutions manage risk responsibly and behave with integrity. Banking, insurance and financial service firms are subject to more controls in terms of auditing, reporting and assessment, not to mention the storage and management of data. It’s a sector where security is crucial – where a data breach can not only have immediate financial consequences but a longer-term impact on reputation and trust. And to make the business of transformation even more complex, it’s an industry associated with siloed data, a reliance on big iron legacy applications and a cultural resistance to change.

Yet there’s good news. Many of the same technologies that are transforming financial services can also help firms in the sector overcome these challenges. In particular, IBM technologies have a proven history of driving transformation forward.

The technology behind future finance

Take IBM’s Watson AI technologies, for example. On the one hand, they’re helping firms deliver mobile apps that can combine data from public sources, financial sector sources and other client interactions to give customers information they can use in their financial decisions. On the other hand, they’re giving in-house sales teams the tools they need to ask for information or guidance using natural language, and get an effective, data-driven response in the same digestible format.

Meanwhile, firms are using AI to prevent fraud and manage risk, using Watson’s ability to ingest vast amounts of data – both at rest and in real-time – and spot patterns or inconsistencies that need to be flagged. Data can be drawn from existing sources or aggregated from multiple-systems in real-time, ensuring risk and compliance professionals can interpret complex issues and ensure they have the right controls in place. Experience has shown Watson identifying 30% to 50% of anti-money-laundering alerts as false positives and reducing the time it took for a banker to perform customer due diligence on a standard business from over 13 minutes down to five minutes 20 seconds. Nor is this the only way Watson can help firms with their Governance, Risk and Compliance duties; because the technology learns and can work with natural language, it can ingest and interpret regulations as they change.

Cloud also has a crucial role to play. IBM Cloud for Financial Services is a cloud-based platform and ecosystem designed to meet the needs of financial institutions. It comes with technologies like Blockchain and predictive analytics built-in, plus the APIs, reference architectures and microservice templates that can help firms build and deploy their own applications faster. Specific APIs for financial risk management, simulated instrument analytics and control of financial data can aid firms in meeting their governance, risk and compliance obligations. Best of all, firms don’t need to invest in their own infrastructure and build everything from scratch; digital transformation can be an ongoing cost rather than a huge upfront investment.

Data management and protection is a big concern for firms, but IBM technologies can help. IBM’s Guardiam technologies make it easier to identify security and compliance risks, then use tokenisation and pseudonymisation of sensitive data to reduce them. Security teams can set policies to ensure that departments get the information they need to do their jobs, but not information that might add unnecessary risks. Multi-cloud data encryption can safeguard that data across single clouds, multiple clouds or even hybrid environments, while IBM’s Immutable Object Storage technology ensures that companies can set and manage data retention according to regulations, all using a cloud-based interface.

By leading on data management, AI, Blockchain and the cloud, IBM is defining the more collaborative, intelligent financial services platform of the future.

Innovation: The financial industry’s best-kept secret?

18 Apr, 2019

The financial services sector (FSS) has reached a tipping point; should it stay the same and hope for the best or should it embrace disruption and associated technologies and emerge different, stronger and better from its legacy cocoon?

But do FSS firms really need to change at all? Perhaps what does need to change is how they are perceived. Indeed, with a reputation of being not just slow, but reluctant to change, FSS organisations have actually been innovating all the while behind the scenes. Their downfall, perhaps, lies in not shouting loudly about it as many other sectors have done.

So, why are those in the industry now starting to talk much more openly about technology and the impact it can have not just on operations, but the customer experience?

We have reached the point where banks, in particular, must consider and position themselves not just as financial entities, but as lifestyle brands too, according to Bharat Bhushan, CTO of banking and financial markets at IBM’s Financial Services division.

“The industry has been innovating in a pull and a push manner. Our ability to interact with our banks using mobile devices doesn’t sound like an innovation, but it isn’t that long ago that we were walking into branches and checking ATMs. Now, people can check their balance several times a day while waiting for trains/planes etc.” he says. 

“It’s important to distinguish between the incumbents and the challengers. FinTech has been one of the reasons for banks to innovate – if they don’t innovate, their lunch will be eaten.”

The devil is in the detail when it comes to moving innovation from theory to reality, though, with execution becoming the real differentiator, according to a recent blog post by Bhushan.

“An organisation with a culture of innovation, collaboration and true customer focus will be able to maintain differentiation and identity in the digital world as they do in the physical world. The winners will use their digital capabilities to draw intelligence from data in real-time and use it to drive behaviour change or, convenience,” he added.

Turning adversity into opportunity

With an industry changing almost beyond recognition, despite historic innovation, many FSS organisations feel somewhat unsettled.

Indeed, most of those in the sector entered 2019 feeling less certain about the future than ever.

“[This uncertainty can be] quite uncomfortable for some organisations. They’re thinking ‘we’ve got to change, but we don’t really know where to start.’ We really try and structure the way we help companies by looking at those opportunities. Sometimes they just need a bit of help to figure out how to combine the technology with the business aspects and the user side of things. We can help them get started on the road and often getting started is the hardest bit,” adds Holly Cummins, worldwide development lead of the IBM Cloud Garage.

“Once companies see they can innovate and nothing terrible happened that is a seed for something that can then ripple out through the organisation and help them innovate in other ways. It’s testing the water and seeing what happens and that takes away a lot of the fear.”

In engagements with businesses, these pilots or test cases are dubbed ‘minimum viable products’ according to Cummins.

Cummins adds: “We worked on a project years ago with a bank that had quite a large budget set aside for something. It was really innovative around allowing their customers who collected loyalty points to pay with them…

“We tried something smaller. Everybody said it was wonderful, it was innovative but they didn’t want it – their partners just weren’t able to digest it – even though everybody agreed it was great. So, even though the project failed in one sense, the bank was actually delighted as they hadn’t wasted money and knew what to do differently if they tried it again. A good thing came out of something that could be perceived as a failure or negative.”

It will be the types of organisations that turn negatives into positives that, ultimately, win out.

Open banking, for example, means the industry has much more to gain than it stands to lose.

“When everyone becomes digital, the big challenge for financial institutions is how to differentiate themselves from the nearest competitor. That’s where the magic will start to happen,” Bhushan adds.

“Open Banking requires a cultural shift in a financial institution. Once you form a culture where you are not just behaving like a bank… Open APIs and banking are a fundamental shift from a very closed industry to one on its way to becoming an open platform.

“Historically, you and I have been generating data for these banks for the last 60/70 years since computers were used. That data belonged to the bank. But with open APIs, that data belongs to us. Regulations like GDPR have helped empower that.”

Levelling the playing field

Advanced technologies are now no longer the preserve of large enterprises or those with infinite pots of cash. Now, all organisations can benefit from the speed and scale of subscription-based services that deliver business-level results in almost a consumer-friendly consumption model. 

“Financial institutions need to address how ideas are generated and executed. It’s about failing fast. They should be using the cloud, for example, as a fundamental mechanism. Cloud and everything that goes with cloud is fundamental to that change,” according to Bhushan.

“DevOps in itself is a big shift for some banks – globally not just in the UK. The idea of bottom up and top down innovation [is very new].”

Continuous delivery is an important weapon to have in your arsenal as an FSS organisation, according to Jim McKay, worldwide solutions architect at IBM SoftLayer.

“Ultimately, it’s about how quickly Solutions can be developed. How can you evolve the [old] ways to become more agile? And that’s really where we’re seeing the opportunity for cloud,” he says.

The cloud and emerging technologies such as AI and machine learning serve as both a catalyst for and a reason to change for the financial industry. Customers, ultimately, expect the same – if not greater – level of tech sophistication they’re used to in their consumer lives when it comes to everyday tasks such as banking.

Every element of work carried out in the FSS is being transformed by technology and AI represents a $16 trillion opportunity, according to IBM’s Tiffany Winman reporting on all the industry news and views coming from IBM’s Think 2019 event earlier this year.

It’s an opinion industry experts share, with analyst firm Gartner suggesting that AI implementation grew by 270% in the last four years and 37% in the last year alone. This, says Winman, is helping firms digitally reinvent themselves and using AI to reduce costs, create new revenue streams and enhance the customer experience.

But there remains some fear, uncertainty and doubt (FUD) around AI, with concerns specifically focused on job loss or displacement.

“IBM’s approach to AI is not to replace humans, but rather to create augmented intelligence that helps amplify human cognition,” Winman wrote.

“Companies should ask: How do you leverage technology to help humans do what they do, better? And how can technology bring value in such a way that it allows them to do higher value things?”

Rob Thomas, IBM General Manager of Data and AI, has another way of looking at it, saying at Think 2019: “AI is not going to replace managers, but managers who use AI will replace the managers who do not.”

Thomas said AI was the “new electricity” which should certainly serve as a warning to those who are still in any doubt as to the transformative powers it possesses for businesses of all sectors but, specifically, the financial industry.

Partnering remains key to success

Like every other industry, it’s important for those in the FSS to recognise they don’t have to go it alone. 

“Banks need to open up to the idea of partnering with other companies and find the right balance between investing in FinTech or partnering. Finding that balance of using FinTech to innovate incrementally or in a process means we finally have a win/win scenario,” Bhushan says, adding its an innovation inhibitor if those organisations are so proprietary that they simply can’t – rather than won’t work with anyone else.

Blockchain, for example, is a key innovation that offers much to FSS firms. However, up until recently, its brilliance had gotten mixed up and somewhat lost in the hype surrounding crypto currencies, according to Bhushan.

“I’ve certainly seen a shift [in that thinking] now,” he says. “Blockchain works really well when you have multiple parties. In a mortgage situation, for example, you can have the land registry, banks – all of them participating in the Blockchain. But, it needs all of those parties to come to the table and agree to the standards.”

The real 21st century currency 

Against the backdrop of disruption and innovation, those in the FSS are facing the same security threats – often intensified – as many other industries.

“Cyber security is as much a business problem as a technology one. Every employee is a cyber security manager,” Sean McKee, senior manager of cyber threat management at TD Bank, told delegates at Think 2019.

“What can an organisation do to prepare? Your plan is not worth the paper it’s written on if nobody knows how to use it… TD Bank did a five month workup for a two day test. The president of the US bank immediately saw the results of their decisions,” he continued.

McKee outlined four key steps to effective implementation:


  1. Exercise and test your strategy and plan. Come to a cyber range and bring your playbook

  2. Technical security controls testing (ethical hacking committee)

  3. Resource for success. It takes a long time to produce a proper exercise

  4. Continuous improvement

Security and resilience can often be seen as more of a burden than compliance in the FSS sector, but it can also unlock many positives, according to Bhushan.

“I think security can be a very empowering mechanism to enable trust between you and your customers and partners at all levels,” he says.

“In the 21st century, information is money. So, by being secure you are actually accelerating the trust your suppliers and partners have in you and accelerating business results.”

In a world that is travelling in all sorts of different directions at 100 miles per hour, the temptation to simply hit the pause button to take stock can be incredibly tempting. However, by embracing the cloud, continuous development and DevOps, FSS firms can continue to keep the lights on, defend against threats and innovate, too.

“Organisations can no longer look to their competitors to decide what to do next. Innovation and reinvention is key to existence in this rapidly changing world. Delivering customers’ needs with agility and pace is vital. Organisations should start on their journey by exploring how data and AI together can uncover the value hidden in their data and then deliver features with simplicity,” Bhushan adds.

“Digital is a prerequisite and a journey, it is not the destination. Creating magical experiences that consumers will pay for is the end game.”

The cloud news categorized.